FREE LIVE TRAINING · | · VIA ZOOM
FREE LIVE MASTERCLASS
| · VIA ZOOM
FOR CANADIAN HOMEOWNERS WITH 30% EQUITY AND MONEY LEFT OVER EVERY MONTH
How Disciplined Canadian Homeowners Could Knock 10 Years Off Their Mortgage using the paycheque and savings they already have
In this free 45-minute training, I’ll show you how an offset mortgage puts the money you already earn to work against your mortgage, and how many years it could take off yours. No earning more. No cutting back.
Hosted by Charles Kornbluth · 20 years in mortgages Stay to the end and get the Mortgage Free Date Worksheet. No spam. Just your confirmation and a couple of reminders before we go live.
I'll send the audit to your inbox in the next two minutes - no spam, no funnels, just the four numbers and a quiet read on what they mean.
FREE LIVE TRAINING · | · VIA ZOOM
FOR CANADIAN HOMEOWNERS WITH 30% EQUITY AND MONEY LEFT OVER EVERY MONTH
How Disciplined Canadian Homeowners Could Knock 10 Years Off Their Mortgage using the paycheque and savings they already have
In this free 45-minute training, I’ll show you how an offset mortgage puts the money you already earn to work against your mortgage, and how many years it could take off yours. No earning more. No cutting back.
Hosted by Charles Kornbluth · 20 years in mortgages Stay to the end and get the Mortgage Free Date Worksheet. No spam. Just your confirmation and a couple of reminders before we go live.
I'll send the audit to your inbox in the next two minutes - no spam, no funnels, just the four numbers and a quiet read on what they mean.
FREE LIVE TRAINING · | · VIA ZOOM
FREE LIVE MASTERCLASS
| · VIA ZOOM
FOR CANADIAN HOMEOWNERS WITH 30% EQUITY AND MONEY LEFT OVER EVERY MONTH
How Disciplined Canadian Homeowners Could Knock 10 Years Off Their Mortgage using the paycheque and savings they already have
In this free 45-minute training, I’ll show you how an offset mortgage puts the money you already earn to work against your mortgage, and how many years it could take off yours. No earning more. No cutting back.
Hosted by Charles Kornbluth · 20 years in mortgages Stay to the end and get the Mortgage Free Date Worksheet. No spam. Just your confirmation and a couple of reminders before we go live.
I'll send the audit to your inbox in the next two minutes - no spam, no funnels, just the four numbers and a quiet read on what they mean.
Real Numbers. Real Couples. Real Headway.
CASE STUDY #1
Married, late 50s, retiring in the next 10 years.
Their renewal offer had a great rate, and would still take 18 years to pay off.
We set up an offset mortgage so their income and savings work against the balance every day.
Result:
A PLAN TO BE MORTGAGE FREE IN 8 YEARS INSTEAD OF 18. DONE BEFORE RETIREMENT.
- A. F.
CASE STUDY #2
Married, good income.
Credit card and personal loan debt eating the budget every month.
We rolled it all into one offset mortgage.
Result:
$1,200 A MONTH BACK IN THEIR POCKET. MORTGAGE ON TRACK TO BE PAID OFF 6 YEARS SOONER.
- K. K.
Based on each household's own numbers. Most are plans in progress. Yours will be different.
Real Numbers. Real Couples. Real Headway.
CASE STUDY #1
Married, late 50s, retiring in the next 10 years.
Their renewal offer had a great rate, and would still take 18 years to pay off.
We set up an offset mortgage so their income and savings work against the balance every day.
Result:
A PLAN TO BE MORTGAGE FREE IN 8 YEARS INSTEAD OF 18. DONE BEFORE RETIREMENT.
- A. F.
CASE STUDY #2
Married, good income.
Credit card and personal loan debt eating the budget every month.
We rolled it all into one offset mortgage.
Result:
$1,200 A MONTH BACK IN THEIR POCKET. MORTGAGE ON TRACK TO BE PAID OFF 6 YEARS SOONER.
- K. K.
Based on each household's own numbers. Most are plans in progress. Yours will be different.
Real Numbers. Real Couples. Real Headway.
CASE STUDY #1
Married, late 50s, retiring in the next 10 years.
Their renewal offer had a great rate, and would still take 18 years to pay off.
We set up an offset mortgage so their income and savings work against the balance every day.
Result:
A PLAN TO BE MORTGAGE FREE IN 8 YEARS INSTEAD OF 18. DONE BEFORE RETIREMENT.
- A. F.
CASE STUDY #2
Married, good income.
Credit card and personal loan debt eating the budget every month.
We rolled it all into one offset mortgage.
Result:
$1,200 A MONTH BACK IN THEIR POCKET. MORTGAGE ON TRACK TO BE PAID OFF 6 YEARS SOONER.
- K. K.
Based on each household's own numbers. Most are plans in progress. Yours will be different.
Sound Familiar?
You make more than you spend, and you've never missed a payment.
But on a $500,000 mortgage at 4.5%, about $33,000 goes out in the first year, and only about $11,000 of it comes off the balance.
You've tried what everyone suggests: biweekly payments, a lump sum in spring, shopping 3 places for a quarter point. The balance still crawls.
You want to be debt-free sooner, without changing how you live.
This is for you if:
You've built up 30% or more equity in your home
You have money left over most months, and you track where every dollar goes
Your paycheque lands in chequing and sits there while your mortgage charges interest every day
Your renewal is coming up at 2 or 3 times your old rate, and "just sign it" doesn't feel like a plan
You don't want to cut back on your life. You just want every payment to finally get you somewhere
Sound Familiar?
You make more than you spend, and you've never missed a payment.
But on a $500,000 mortgage at 4.5%, about $33,000 goes out in the first year, and only about $11,000 of it comes off the balance.
You've tried what everyone suggests: biweekly payments, a lump sum in spring, shopping 3 places for a quarter point. The balance still crawls.
You want to be debt-free sooner, without changing how you live.
This is for you if:
You've built up 30% or more equity in your home
You have money left over most months, and you track where every dollar goes
Your paycheque lands in chequing and sits there while your mortgage charges interest every day
Your renewal is coming up at 2 or 3 times your old rate, and "just sign it" doesn't feel like a plan
You don't want to cut back on your life. You just want every payment to finally get you somewhere
Sound Familiar?
You make more than you spend, and you've never missed a payment.
But on a $500,000 mortgage at 4.5%, about $33,000 goes out in the first year, and only about $11,000 of it comes off the balance.
You've tried what everyone suggests: biweekly payments, a lump sum in spring, shopping 3 places for a quarter point. The balance still crawls.
You want to be debt-free sooner, without changing how you live.
This is for you if:
You've built up 30% or more equity in your home
You have money left over most months, and you track where every dollar goes
Your paycheque lands in chequing and sits there while your mortgage charges interest every day
Your renewal is coming up at 2 or 3 times your old rate, and "just sign it" doesn't feel like a plan
You don't want to cut back on your life. You just want every payment to finally get you somewhere
Even if you...
Think you've left it too late
Were told you have to wait until renewal to change anything
Are self-employed and your income goes up and down
Have heard of offset mortgages and assumed they're too good to be true
If any of that sounds like you, I'd love to have you in the room.
Even if you...
Think you've left it too late
Were told you have to wait until renewal to change anything
Are self-employed and your income goes up and down
Have heard of offset mortgages and assumed they're too good to be true
If any of that sounds like you, I'd love to have you in the room.
Even if you...
Think you've left it too late
Were told you have to wait until renewal to change anything
Are self-employed and your income goes up and down
Have heard of offset mortgages and assumed they're too good to be true
If any of that sounds like you, I'd love to have you in the room.
HERE'S WHAT YOU'LL LEARN
HOW YOUR PAYCHEQUE CAN PAY DOWN YOUR MORTGAGE EVERY DAY
Your paycheque, savings and mortgage sit in one account. Every dollar you don't spend lowers your balance and the interest you pay, and it's still yours to use.
$108,000 LESS INTEREST, EVEN AT A HIGHER RATE
A real example, side by side. One couple on a regular mortgage vs an offset mortgage: about 7.5 years sooner and about $108,000 less interest. Then I'll show what happens if rates go up 1%.
HOW TO TELL IN 5 MINUTES IF IT'S RIGHT FOR YOU
The quick test I use before I recommend it, what it costs to switch, who it isn't for, and the 1 mistake that makes it backfire.
HERE'S WHAT YOU'LL LEARN
HOW YOUR PAYCHEQUE CAN PAY DOWN YOUR MORTGAGE EVERY DAY
Your paycheque, savings and mortgage sit in one account. Every dollar you don't spend lowers your balance and the interest you pay, and it's still yours to use.
$108,000 LESS INTEREST, EVEN AT A HIGHER RATE
A real example, side by side. One couple on a regular mortgage vs an offset mortgage: about 7.5 years sooner and about $108,000 less interest. Then I'll show what happens if rates go up 1%.
HOW TO TELL IN 5 MINUTES IF IT'S RIGHT FOR YOU
The quick test I use before I recommend it, what it costs to switch, who it isn't for, and the 1 mistake that makes it backfire.
HERE'S WHAT YOU'LL LEARN
HOW YOUR PAYCHEQUE CAN PAY DOWN YOUR MORTGAGE EVERY DAY
Your paycheque, savings and mortgage sit in one account. Every dollar you don't spend lowers your balance and the interest you pay, and it's still yours to use.
$108,000 LESS INTEREST, EVEN AT A HIGHER RATE
A real example, side by side. One couple on a regular mortgage vs an offset mortgage: about 7.5 years sooner and about $108,000 less interest. Then I'll show what happens if rates go up 1%.
HOW TO TELL IN 5 MINUTES IF IT'S RIGHT FOR YOU
The quick test I use before I recommend it, what it costs to switch, who it isn't for, and the 1 mistake that makes it backfire.
Why Live Matters
The most valuable part only happens live. Bring your own numbers, ask me anything about your mortgage, and I'll answer it right there on the call.
The replay won't answer your questions. And it only stays up for 48 hours.
Honestly, the couples who show up together are the ones who actually do something with what they learn. I'd rather have you both live for 45 focused minutes than half-watching a replay you'll probably never get to.
Stay to the end and I'll send you the Mortgage Free Date Worksheet.
Block the time. Show up live. Bring your partner and last year's mortgage statement.
Why Live Matters
The most valuable part only happens live. Bring your own numbers, ask me anything about your mortgage, and I'll answer it right there on the call.
The replay won't answer your questions. And it only stays up for 48 hours.
Honestly, the couples who show up together are the ones who actually do something with what they learn. I'd rather have you both live for 45 focused minutes than half-watching a replay you'll probably never get to.
Stay to the end and I'll send you the Mortgage Free Date Worksheet.
Block the time. Show up live. Bring your partner and last year's mortgage statement.
Why Live Matters
The most valuable part only happens live. Bring your own numbers, ask me anything about your mortgage, and I'll answer it right there on the call.
The replay won't answer your questions. And it only stays up for 48 hours.
Honestly, the couples who show up together are the ones who actually do something with what they learn. I'd rather have you both live for 45 focused minutes than half-watching a replay you'll probably never get to.
Stay to the end and I'll send you the Mortgage Free Date Worksheet.
Block the time. Show up live. Bring your partner and last year's mortgage statement.
Why the usual tips haven't worked...
Most mortgage advice comes as tips. Switch to biweekly. Add a lump sum. Shop for a quarter point.
They help a little. (Biweekly on $500,000 at 4.5% takes about 3 years off.) But they only touch the payment.
I'll walk you through The Headway Method, the 4-step process I use with every client: Map. Math. Meet. Move.
You'll leave with a clear picture of what's possible from where you are. Whether you ever work with me or not, the information is yours to keep.
Why the usual tips haven't worked...
Most mortgage advice comes as tips. Switch to biweekly. Add a lump sum. Shop for a quarter point.
They help a little. (Biweekly on $500,000 at 4.5% takes about 3 years off.) But they only touch the payment.
I'll walk you through The Headway Method, the 4-step process I use with every client: Map. Math. Meet. Move.
You'll leave with a clear picture of what's possible from where you are. Whether you ever work with me or not, the information is yours to keep.
Why the usual tips haven't worked...
Most mortgage advice comes as tips. Switch to biweekly. Add a lump sum. Shop for a quarter point.
They help a little. (Biweekly on $500,000 at 4.5% takes about 3 years off.) But they only touch the payment.
I'll walk you through The Headway Method, the 4-step process I use with every client: Map. Math. Meet. Move.
You'll leave with a clear picture of what's possible from where you are. Whether you ever work with me or not, the information is yours to keep.
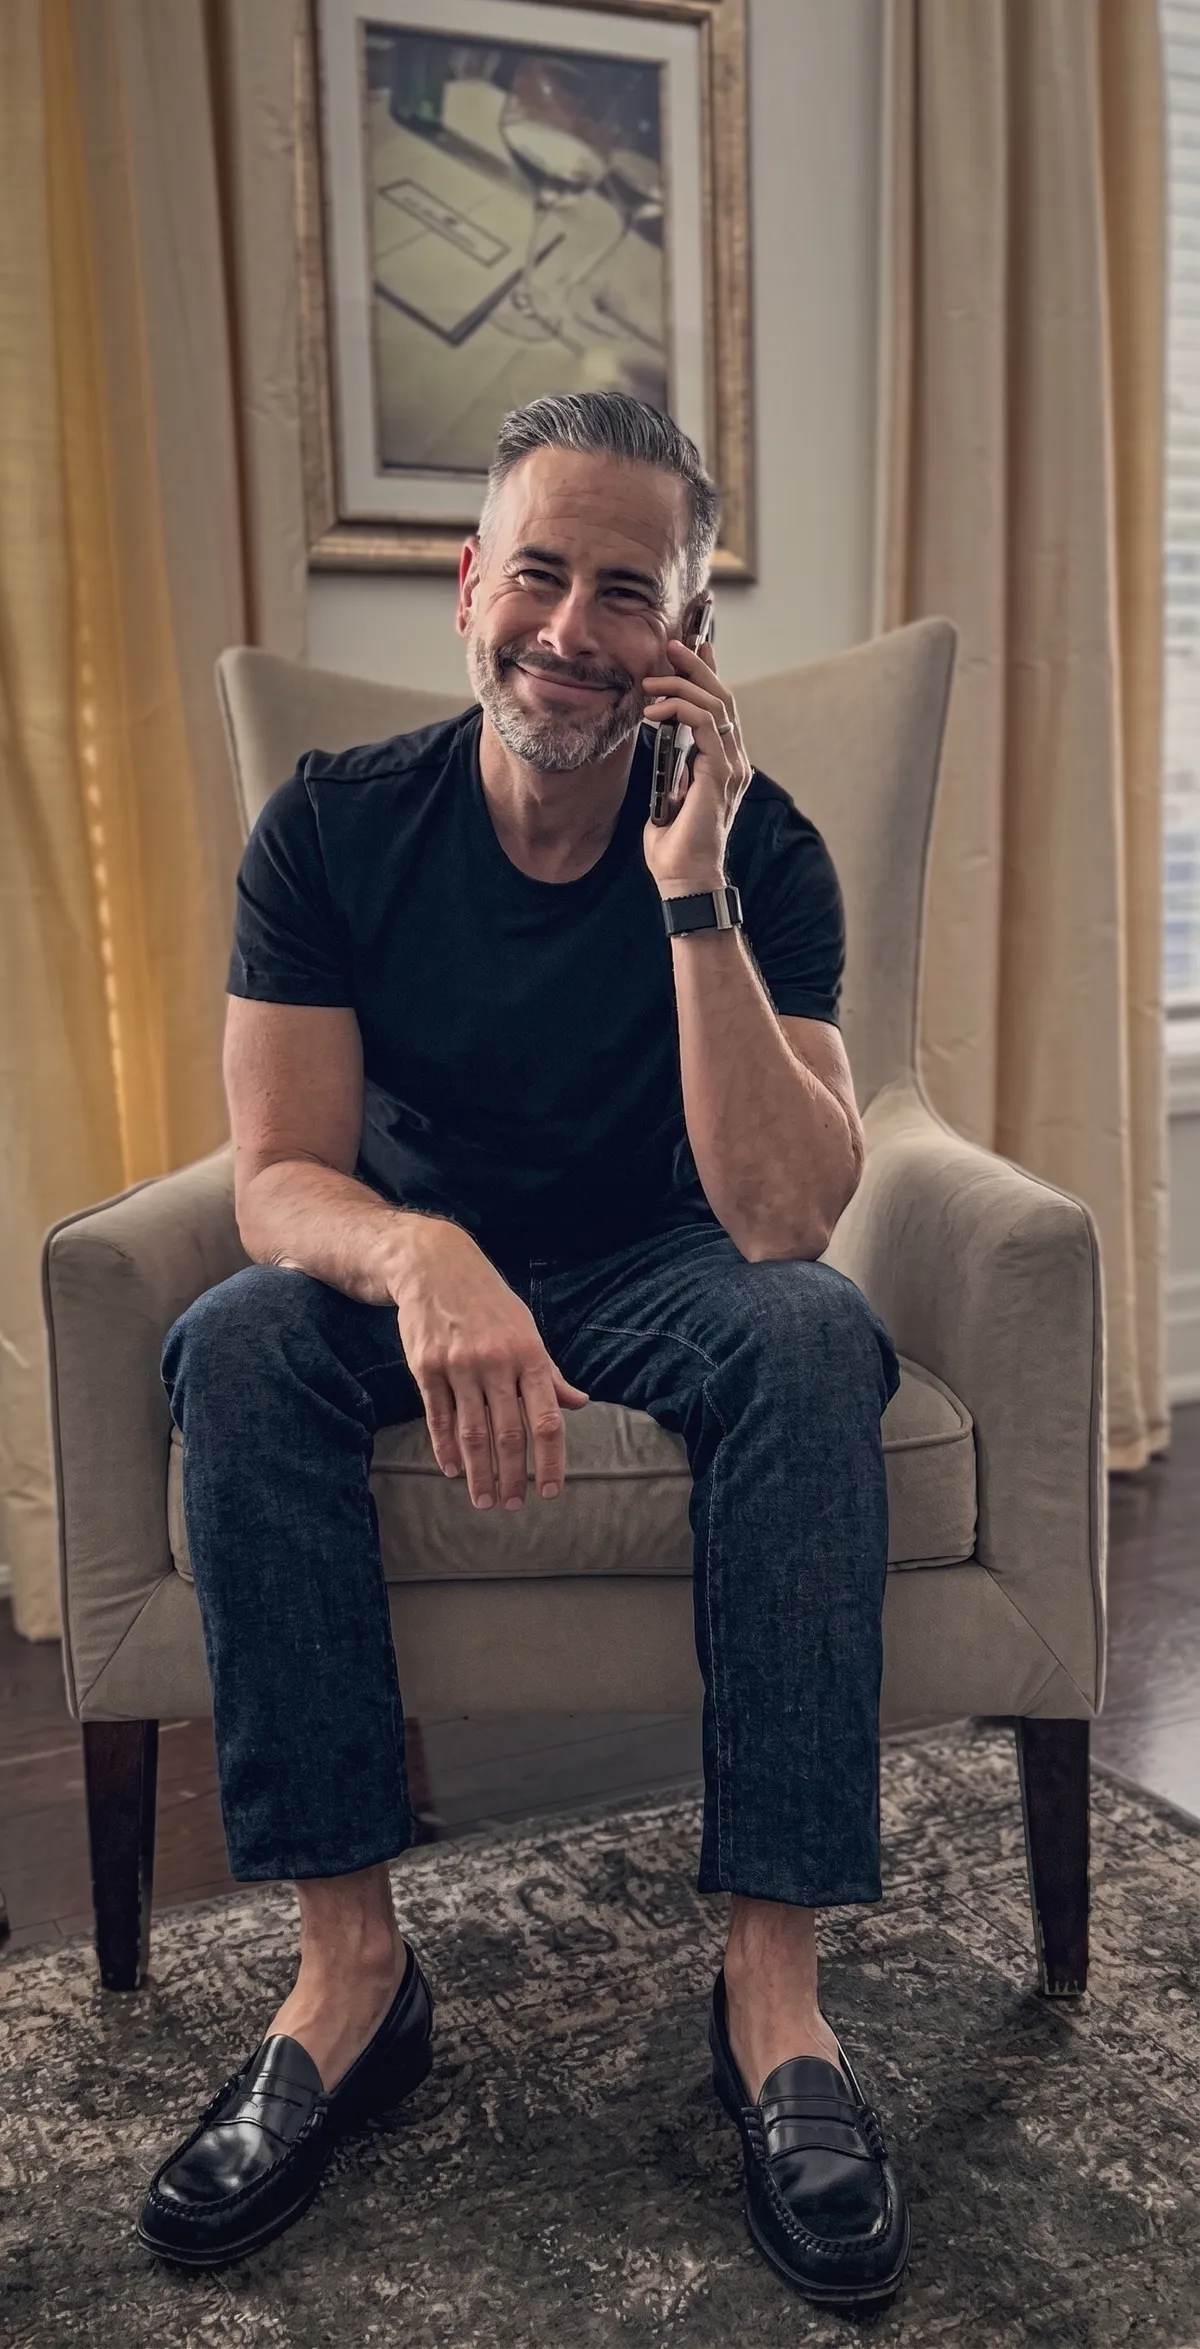
MEET YOUR HOST
Hey! I'm Charles Kornbluth
I've spent 20 years in mortgages, 11 of them at a big bank. I'm a mortgage nerd (I read statements for fun), a dad of 3, and most weekends you'll find me at the ball diamond with a coffee.
I spent the first 15 years of my career getting people into great mortgages. I want to spend the last 10 getting people out of them.
Offset mortgages are now about a third of the work I do. I look at a household's cash flow the way a business reads its books. When an offset mortgage fits, I show you in plain numbers how to start making real headway. And when it doesn't fit, I'll tell you.
Every payment should get you somewhere.
MEET YOUR HOST
Hey! I'm Charles Kornbluth
I've spent 20 years in mortgages, 11 of them at a big bank. I'm a mortgage nerd (I read statements for fun), a dad of 3, and most weekends you'll find me at the ball diamond with a coffee.
I spent the first 15 years of my career getting people into great mortgages. I want to spend the last 10 getting people out of them.
Offset mortgages are now about a third of the work I do. I look at a household's cash flow the way a business reads its books. When an offset mortgage fits, I show you in plain numbers how to start making real headway. And when it doesn't fit, I'll tell you.
Every payment should get you somewhere.
MEET YOUR HOST
Hey! I'm Charles Kornbluth
I've spent 20 years in mortgages, 11 of them at a big bank. I'm a mortgage nerd (I read statements for fun), a dad of 3, and most weekends you'll find me at the ball diamond with a coffee.
I spent the first 15 years of my career getting people into great mortgages. I want to spend the last 10 getting people out of them.
Offset mortgages are now about a third of the work I do. I look at a household's cash flow the way a business reads its books. When an offset mortgage fits, I show you in plain numbers how to start making real headway. And when it doesn't fit, I'll tell you.
Every payment should get you somewhere.
REGISTER FREE BEFORE
One couple in their late 50s now has a plan to be mortgage-free in 8 years instead of 18. Another freed up $1,200 a month and is on track to pay off their mortgage 6 years sooner. I'd love to walk you through how.
It's free, there's no pressure, and if an offset mortgage doesn't fit your household, I'll tell you. Your next renewal is coming either way. The earlier you look, the more options you have.
Block 45 minutes. Bring your partner and last year's mortgage statement. I'll see you there.
REGISTER FREE BEFORE
One couple in their late 50s now has a plan to be mortgage-free in 8 years instead of 18. Another freed up $1,200 a month and is on track to pay off their mortgage 6 years sooner. I'd love to walk you through how.
It's free, there's no pressure, and if an offset mortgage doesn't fit your household, I'll tell you. Your next renewal is coming either way. The earlier you look, the more options you have.
Block 45 minutes. Bring your partner and last year's mortgage statement. I'll see you there.
REGISTER FREE BEFORE
One couple in their late 50s now has a plan to be mortgage-free in 8 years instead of 18. Another freed up $1,200 a month and is on track to pay off their mortgage 6 years sooner. I'd love to walk you through how.
It's free, there's no pressure, and if an offset mortgage doesn't fit your household, I'll tell you. Your next renewal is coming either way. The earlier you look, the more options you have.
Block 45 minutes. Bring your partner and last year's mortgage statement. I'll see you there.
HOME SWEET LOAN INC. | 2026
Privacy Policy | Terms & Conditions
This site is not a part of the Facebook or Instagram apps or apart of Meta Inc. Additionally, this site is NOT endorsed by Facebook or Instagram in any way. FACEBOOK and INSTAGRAM are trademarks of Meta, Inc. Results are not guaranteed and vary by individual situation. These are examples of results from real clients of Marnie Golen, Mortgage Agent Level 1, Licence ON-M24000393. All mortgage products subject to lender approval and applicable regulations.